Projects
Projects
Most of this is one system, not a set of side projects. A data platform, a factor engine, an orchestration layer and a front end, plus the strategies that run on top and the fundamental research I still do.
The platform
These four are one system, built in the order they depend on each other. The data platform came first because nothing above it is worth much if the inputs are wrong.
Lean Data Platform
The layer everything else stands on: vendor ingestion, point-in-time fundamentals and corporate actions, orchestrated by Dagster across a GitOps-managed Kubernetes cluster.
Meridian factor engine
A factor engine built around four components: prediction, ranking, regime and risk. Each one has to earn its way into the product.
Argus portfolio orchestration
A portfolio operating system. Strategy sleeves produce targets, a portfolio engine builds the book, risk overlays cap it, and the execution layer works the orders through to the broker.
PortDash
One dashboard over the whole platform: NAV and attribution, live factor scores, backtest review and VaR-based risk analysis.
The cluster
Everything above runs on hardware I own and maintain. Two Kubernetes clusters across two sites, managed as code, with a self-hosted GitLab underneath it all.
Self-hosting
It started with a 2012 Mac Mini and a fresh Ubuntu install. Most of what I know about running things in production, I learned here first.
This site
Hand-written, generated by a script with no dependencies, and served from the same clusters as everything else.
Strategies
The strategies I built before and alongside the platform, and what each one taught me.
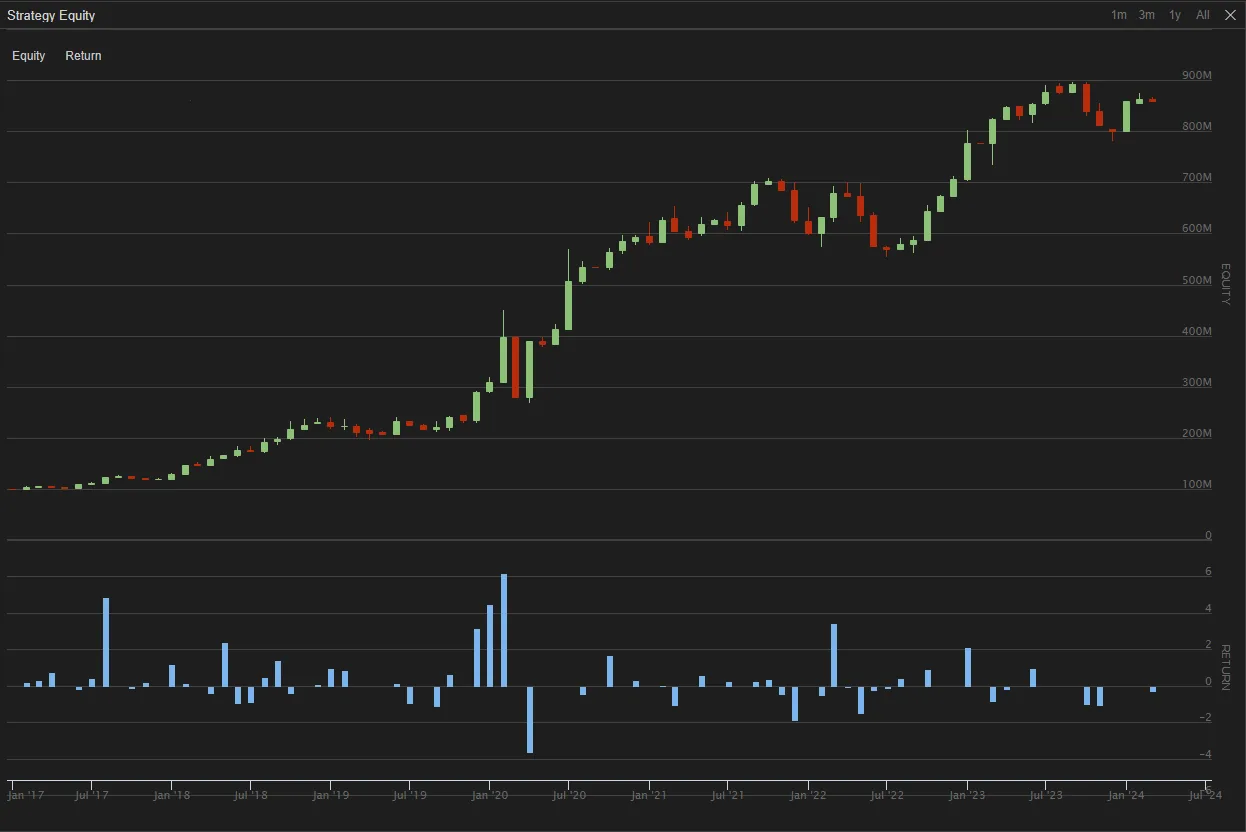
Momentum
Elder's Triple Screen
A long-only momentum strategy that reads three time frames at once. Built for the quant trading module at SMU, and the only thing from that year still running.
Pairs trading within the S&P 500
My first mean-reversion strategy, from the SMU quant trading module. The screen worked. The backtest did not, for reasons I now build guards against.
EMA cross with a put hedge
One of my first QuantConnect strategies. Liquid US stocks in an uptrend, with SPY puts bought when volatility was high. The hedge cost more than it saved.
Markets and research
Valuation, structuring, forecasting and strategy work from SMU and IE.
Eversource Energy equity research
Equity research on Boston's main energy provider: the industry, the financials, and a three-statement model valued several ways, weighted towards the methods that suit a regulated utility.
Structured products proposal
A client case. Rebalance a concentrated equity portfolio and build an income sleeve, using structures instead of going to the market.
What time series models can and cannot forecast
Two projects that answered the same question from opposite ends. Air travel demand forecasts well. Financial returns do not. Their volatility does.
OpenAI and the limits of a first-mover advantage
A case study on whether OpenAI's lead is a structural moat or a fading head start, and why the model layer does not get software economics.