Research into Boston's main energy provider, produced as coursework for Equity Analysis and Portfolio Management at SMU in late 2023. It is a snapshot of what we thought at the time, not a current view on the stock.
Written Q4 2023.
The brief
Eversource is an energy provider serving customers in Massachusetts, Connecticut and New Hampshire. For my SMU Equity Analysis and Portfolio Management class, my group and I compiled a research report covering the company, the industry and competitive landscape, and a full financial analysis of the firm, paired with a model comprising a three-statement build, DCF analysis and comparables analysis.
The view
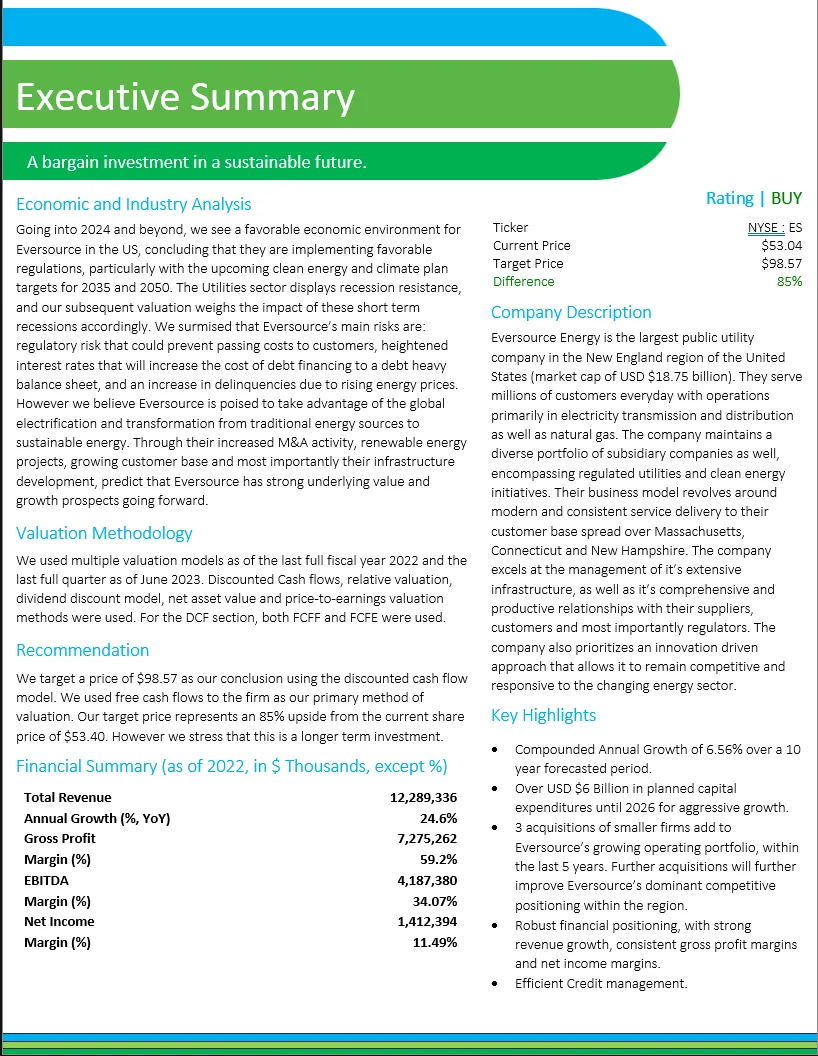
We came out constructive. The regulatory environment looked favourable going into 2024, particularly around the clean energy and climate targets for 2035 and 2050, and utilities as a sector holds up in a recession, which the valuation weighed accordingly.
The risks we landed on were regulatory risk that stops Eversource passing costs through to customers, higher interest rates raising the cost of debt on a balance sheet that already carries a lot of it, and rising delinquencies if energy prices climb.
Against that, the case for the upside was electrification and the shift away from traditional energy, supported by their M&A activity, renewable projects, a growing customer base and above all their infrastructure spending.
All of that was the picture in late 2023. Read it as a worked example of how I get to a view, not a call on the stock today.
The tearsheet
Analysis as of Q4 2023.
- CAGR of 6.56% over the 10-year forecast period.
- Aggressive growth: over USD 6bn of capital expenditure planned through 2026.
- Active M&A: three acquisitions of smaller firms over the last five years, strengthening an already dominant competitive position.
- Robust financials: strong revenue growth, consistent gross profit and net income margins, efficient credit management.